Bitcoin's volatility has plunged, but extreme price swings are more frequent than in 2018
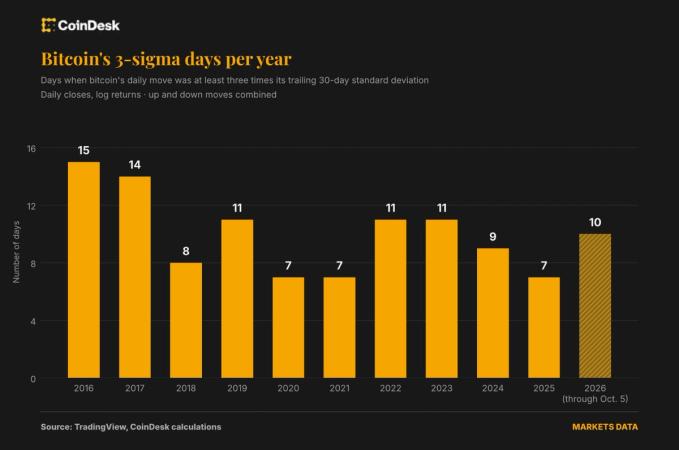
CoinDesk analysis finds 10 unusually large trading days in 2026, raising questions about how investors measure risk in an increasingly institutional crypto market.
Bitcoin BTC$82,486.39 is experiencing more unusually large price swings this year than during the 2018 bear market, even as its overall volatility has fallen sharply, and that's a challenge for anyone relying on standard risk models.
The largest cryptocurrency has recorded 10 days in 2026 when its price moved at least three standard deviations from its recent trading pattern, according to a CoinDesk analysis. That's more than the eight such days recorded during all of 2018, when bitcoin lost 73% of its value.
Traders measure these unusually large moves in ‘sigma,’ a measure of how far an asset's price typically deviates from its normal behavior. To quantify them, CoinDesk compared each day's price move with bitcoin's 30-day realized volatility, a measure of how much its price typically moved each day over the previous month. Any day that moved at least three times that amount, up or down, counted as a ‘3-sigma’ day.
In a normal bell-shaped distribution, about 95% of moves fall within 2-sigma, and 99.7% within three. That makes a 3-sigma move rare, which is why traders use it to flag outsized swings. A high count indicates an asset remains prone to sudden jolts, even if its overall volatility is cooling.
The findings suggest bitcoin has calmed down over the years, but it still has outsized days, and this year it has had them more often than in 2018. This means that bitcoin is experiencing more unusually large moves relative to its recent volatility, even though the moves themselves have become smaller. Bitcoin's annualized volatility is about 46% this year, compared with 84% in 2018, while its 3-sigma moves have averaged roughly 7%, down from about 10% eight years ago.
"Bitcoin still goes through long quiet stretches followed by sharp repricings, and that hasn't changed. The market has matured, with more institutions, ETFs and much deeper liquidity, so the average day is calmer. But the shocks haven't gone away: macro, leverage, positioning," said Nicolas Quatravaux, head of EMEA at Paradigm, the leading institutional liquidity network in crypto derivatives.
This contrast is noticeable even when compared against other volatile assets. Since 2024, bitcoin has been about as volatile as Nvidia, at roughly 47%. Yet it has logged 26 three-sigma days in that time, compared with Nvidia's eight. The S&P 500 had 16, and gold had 12.
The persistence of extreme moves poses a challenge for investors using volatility-based risk models to determine how much bitcoin to hold.
One widely used metric is value-at-risk, or VaR, which estimates how much a portfolio could lose on a bad day. Some VaR models rely heavily on recent price fluctuations, meaning a prolonged stretch of calmer trading can make an asset appear less risky.
Bitcoin's declining 30-, 90-, and 180-day volatility measures could therefore encourage investors to increase their exposure. But depending on how the model is constructed, that apparent reduction in risk may not fully capture the possibility of unusually large losses.
It also estimates a loss threshold but doesn't tell investors how severe losses could become beyond that threshold. This is known as tail risk — the possibility of rare but unusually large losses that fall outside an asset's normal trading pattern. Bitcoin's recurring three-sigma moves illustrate why investors need to consider such extreme outcomes, even as day-to-day volatility declines.
"Standard VaR measures do not properly assess the full tail risk, and this is one of the main reasons industry has been moving towards Expected Shortfall and similar measures, that do take tail risk into account," said Luuk Strijers, CEO of crypto options exchange Deribit.
Expected shortfall looks at how bad losses get on the worst days, not just how often they happen. Unlike VaR alone, this methodology helps investors gauge how damaging those extreme losses could be.
"If tail risk is not considered in the portfolio targets, then a quieter bitcoin does encourage indeed a broader allocation in the portfolio, making sudden jumps have a greater impact in the portfolio," Strijers said.
Market participants point to a volatile mix of unpredictable macro shocks and highly leveraged options positioning as the dual drivers of these high-VaR days.
"It was a slow start, with money rotating out into tech stocks, and a string of DeFi hacks pushed people towards vol selling and structured products for yield. Then you get Trump, the Iran war, the Fed, and with everyone short vol in a range, one headline is enough to give you an outsized day,” he said.
Essentially, the risk builds when traders bet that prices will remain relatively stable. That positioning involved selling (shorting) options, essentially insurance against big price swings, to pocket the premium.
Such strategies work while markets stay quiet. But when a macro headline hits, and prices suddenly face extreme swings, those sellers are caught on the wrong side, and their rush to cover can turn a move into a shock.
Alexander S. Blume, co-founder and CEO of Two Prime, an SEC-Registered Investment Advisor, pointed to one especially popular version of that trade, called call overwriting. Investors sell call options on bitcoin they already own, giving up some of the upside in exchange for steady income from selling the call options.
"I believe that, despite tempered volatility on the whole, the heavy increase in derivatives markets positioning allows for large moves to still occur somewhat frequently. At present, call overwriting is a highly crowded trade. When we see a move up, like the past month, it creates a short squeeze that amplifies the moves," Blume said.
The good news is that the market is absorbing these jolts better than it once did.
On Sept. 21, the day of bitcoin's latest 3-sigma jump, Paradigm facilitated a record $6.7 billion in options trades.
"This time we haven't seen or heard of any desk taking a bad hit," Quatravaux said.
"Participants are much more sophisticated than a few years ago, risk management has improved a lot, and there's more institutional money in the market, so a tough month stays a tough month," he said.
Asanat Analysis — Why it matters
Bitcoin's volatility compression—measured by standard deviation or realized volatility metrics—masks a paradox: while day-to-day swings have contracted, the *frequency* of outsized moves (>5-10% daily swings) has actually increased versus 2018. This suggests volatility is clustering rather than smoothing, likely driven by institutional flows reacting to macro triggers (Fed decisions, risk-off sentiment) in ways retail-dominated markets of 2018 didn't exhibit. The institutional presence that was supposed to reduce volatility may instead be creating regime-dependent shocks.
Traditional risk models (Sharpe ratios, standard deviation) assume normal distributions and thus systematically underestimate tail risk when large moves bunch together. A 2026 portfolio manager relying on lagged volatility metrics could be caught off-guard by sudden 10% swings, even if realized vol appears benign. This mirrors pre-2008 lessons about correlation breakdown during stress. For institutional investors now treating Bitcoin as a portfolio hedge or return driver, the gap between *average* volatility and *tail event* frequency is the actual risk metric that matters.
Historically, 2018 saw sustained directional trends and panic selling; 2026's volatility pattern—lower baseline with higher peak frequency—suggests a market where institutions are quick to rotate or rebalance around news catalysts rather than trend-following. This behavioral shift has implications for derivative pricing and margin management, where assumption of steady-state conditions has failed before.