European Central Bank calls for merchants to participate in digital euro pilot
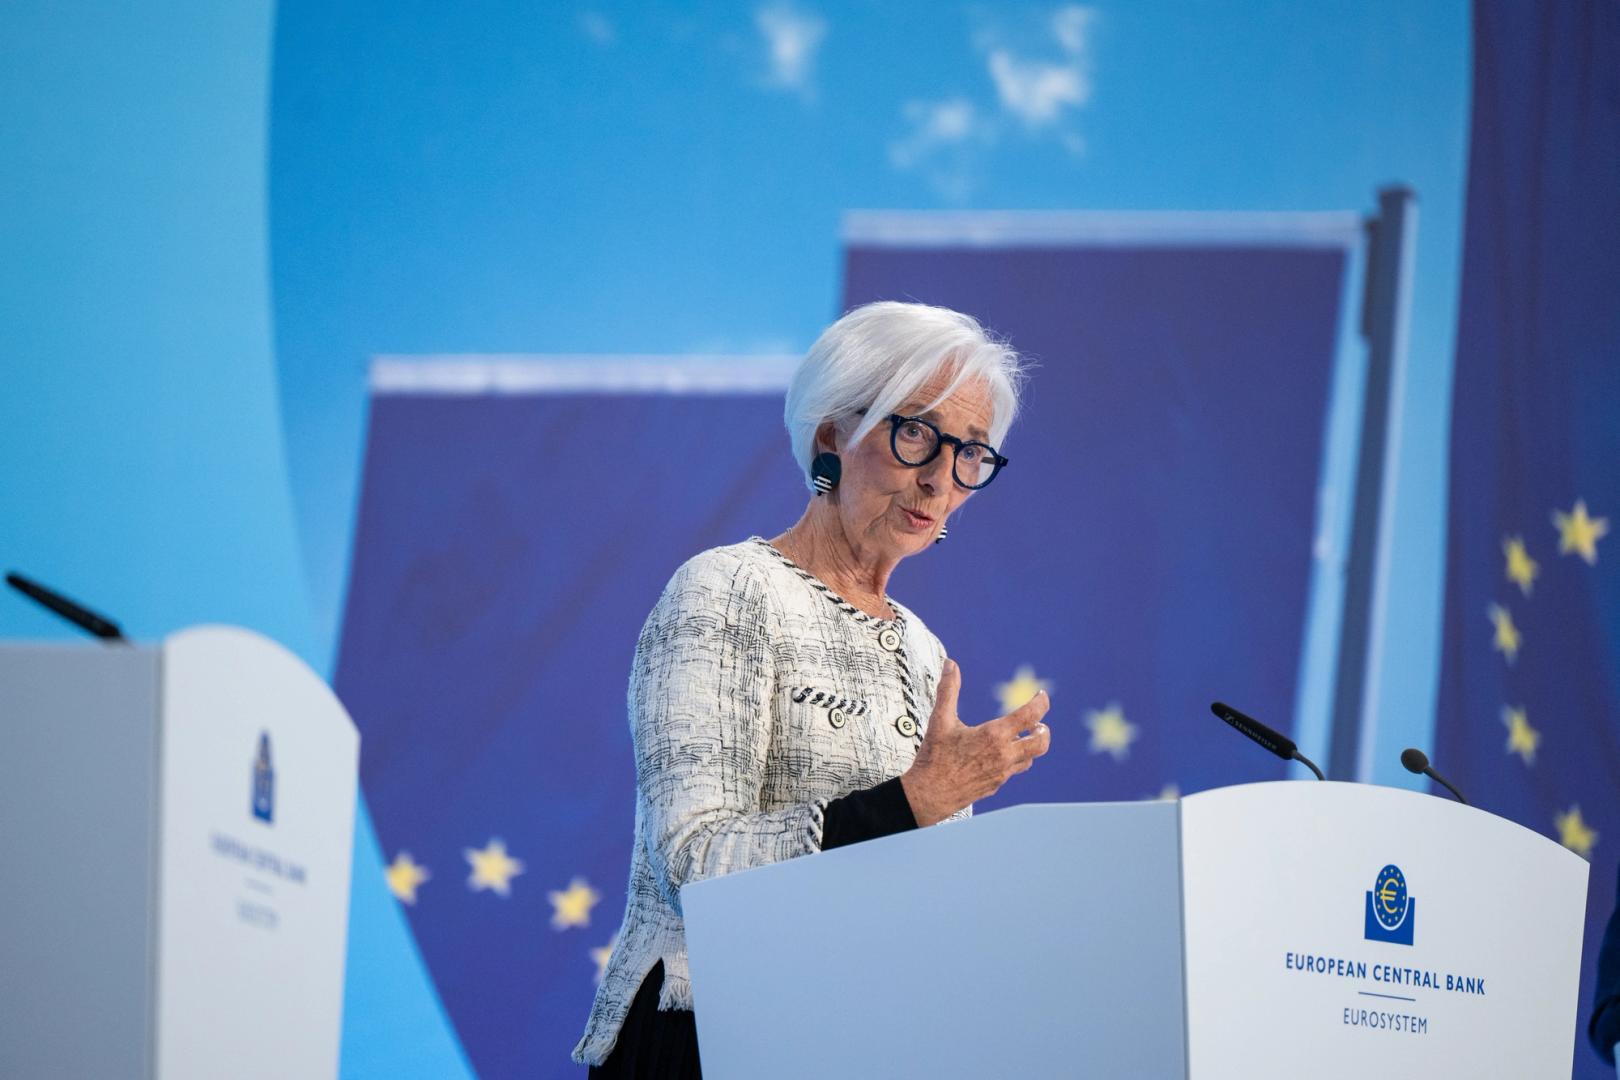
The 12-month test will put a beta version of the central bank currency through online, mobile, in-store and peer-to-peer payments.
The European Central Bank (ECB) on Tuesday called on e-commerce and mobile commerce merchants in the euro zone to join a digital euro pilot as it prepares a retail central bank digital currency (CBDC) for possible issuance in 2029.
The pilot will test the technology, operational processes and user experience of a beta version of the currency, which will resemble the digital euro, but will not be legal tender.
The ECB’s call for merchants is about more than just technical testing. A digital euro will need enough places to spend it if consumers are to use it, making merchant acceptance a commercial question as much as a policy one.
“Many people think the digital euro’s success will depend on how governments and the public sector explain its usefulness,” Isadora Arredondo, vice president of global policy at Hedera, told CoinDesk via LinkedIn. “But the more difficult part will be making the project work commercially.”
Arredondo said merchants would need incentives to join in sufficient numbers and to ensure consumers do not encounter barriers when paying. One option, she said, could be for payment service providers to lower the fees merchants pay to accept digital-euro payments.
The call for merchants comes weeks after the bank selected 36 banks and payment firms to participate in the testing phase. The 12-month pilot is scheduled to begin in the second half of 2027, with the ECB targeting possible issuance in 2029, subject to legislation and a separate Governing Council decision.
The trial will involve the ECB, 19 euro-area national central banks and selected merchants. ECB and national central bank staff will act as users, testing online and offline transfers between individuals, in-store payments, e-commerce purchases and mobile-commerce payments.
While legislation enabling the currency has not been finalized, the ECB is pressing ahead with the project because it views the adoption of private dollar-backed stablecoins, such as Tether's USDT and Circle Internet's USDC, as a threat to Europe’s monetary autonomy.
Tokenized equities lead RWA inflows as the market recovers; Binance's bStocks hit ~$118.5M in two months, now #2 issuer and ~90% of on-chain equity DEX volume.
Asanat Analysis — Why it matters
The ECB's merchant recruitment signals a critical inflection point for European CBDC adoption: technical viability is assumed solved; the real challenge is commercial viability. By explicitly targeting merchants rather than just banking infrastructure, the ECB acknowledges that a digital euro without spending venues is stillborn. This mirrors payment network dynamics where adoption follows utility, not policy mandate. The 2027 pilot-to-2029 issuance timeline compresses a typically longer CBDC runway, suggesting political urgency around stablecoin displacement.
The stated rationale—countering dollar-backed stablecoins and preserving monetary sovereignty—reflects genuine policy anxiety, but the framing inverts the actual merchant problem. USDT and USDC succeed because they offer permissionless integration and lower friction than legacy payment rails; a digital euro bound by regulatory requirements and central bank operational constraints faces inherent structural disadvantages. Fee reduction by payment service providers is mentioned as a potential incentive, but this creates a subsidy burden that diminishes the project's economic logic. The outcome depends on whether regulatory mandate and eurozone-wide adoption can overcome the commercial advantages private stablecoins have already captured.
Success also hinges on a second-order dependency: whether consumers actually demand a CBDC when private alternatives already function. The pilot's peer-to-peer testing component is notable—if digital euros don't outperform existing mobile payments or stablecoins in friction or cost, merchant participation remains extractive rather than voluntary. This CBDC iteration represents the EU's attempt to reassert control over monetary rails; whether that control translates to adoption remains the open question.