Stripe to expand stablecoin cards to over 100 countries by the end of the year
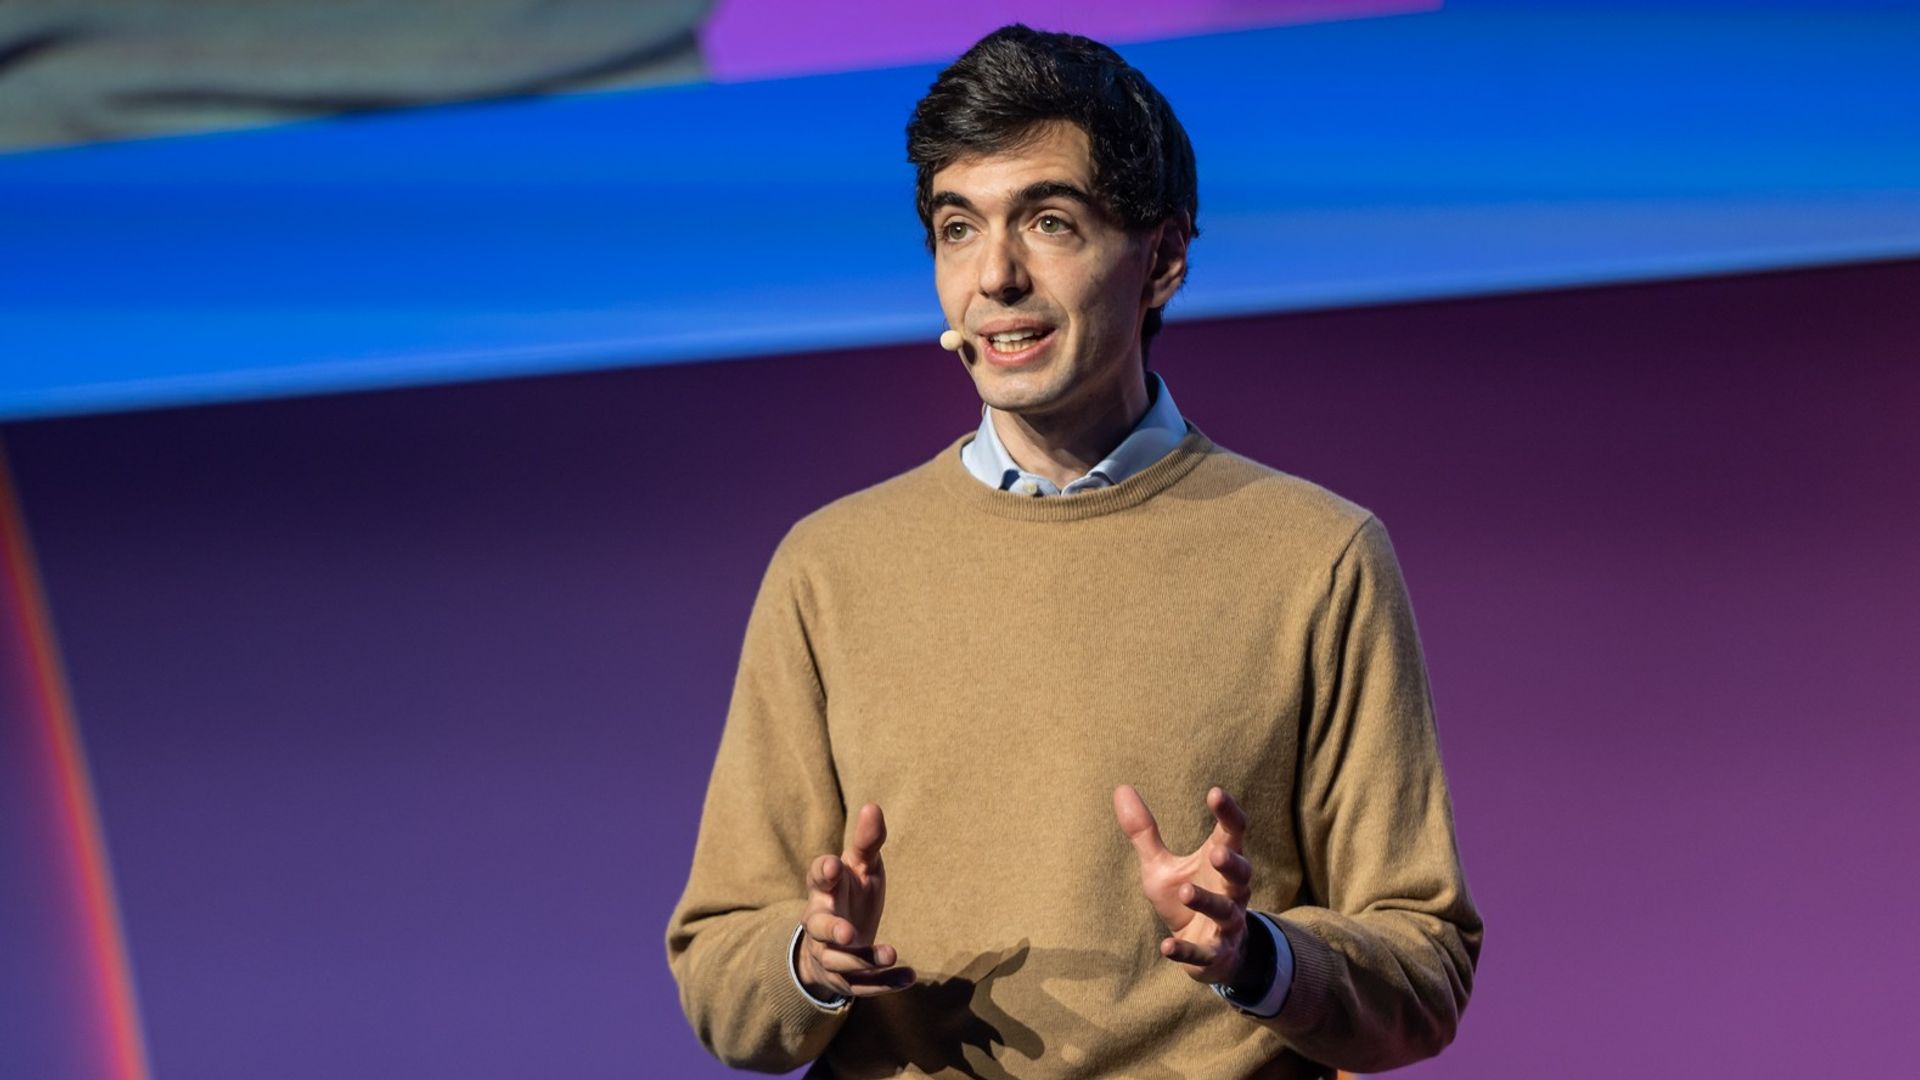
The payments giant is planning a major global expansion for its stablecoin cards business, and is exploring tokenized deposits and DeFi use cases, new crypto head Henri Stern said.
Global payments firm Stripe is expanding its stablecoin cards business globally, betting that digital dollars can become another way for consumers and businesses to pay alongside traditional currencies.
Henri Stern, CEO and co-founder of crypto wallet infrastructure firm Privy acquired last year by Stripe, has taken on an additional role overseeing stablecoins and crypto across Stripe, the company told CoinDesk.
Stripe expects its stablecoin card programs to more than 100 countries by year-end, Stern told CoinDesk in an interview. Current customers include crypto exchange Kraken, fintech Ramp and payments app Morse.
The expansion comes as stablecoin cards emerge as a fast-growing corner of the $300 billion-plus digital dollar market. About $1.2 billion of stablecoins were spent through cards last month, according to Paymentscan, triple the amount a year earlier. That's still a fraction of the global card payments market, but points to stablecoins are increasingly being used beyond crypto trading and cross-border transfers into everyday purchases.
Stripe's approach is to plug them into infrastructure it already has, Stern told CoinDesk.
The company has issued more than 400 million cards and processed hundreds of billions of dollars in card volume since 2018, Stern said. Its stablecoin offering combines that issuing business with Bridge, the stablecoin infrastructure company Stripe bought for $1.1 billion in 2024.
For a company such as Ramp, that could mean taking a corporate card into new countries using stablecoins instead of rebuilding banking and payments connections market by market. Kraken, meanwhile, has explored letting customers spend from accounts where they already hold digital assets.
Stripe has been assembling the pieces for a broader blockchain payments push. After buying Bridge and Privy, it also partnered with crypto investment firm Paradigm to develop Tempo, a blockchain designed for payments. Stripe is also a founding investor in Open Standard, the company developing Open USD, a stablecoin that aims to challenge Circle's USDC and Tether's USDT. Bridge co-founder Zach Abrams recently moved to run Open Standard full time.
Stern said those products are meant to work closely together without locking customers into Stripe's ecosystem.
“If you're using Stripe, Bridge, Privy, Tempo, Open USD, it should be absolutely amazing, and it should feel like these systems were built to exist together,” he said.
The card business follows the same approach. Many programs currently use Circle's USDC, but Stern said Stripe intends to remain “completely stablecoin agnostic, completely blockchain agnostic.”
That fits Stripe's broader vision: stablecoins, Stern said, should become another option inside products businesses already use, rather than a separate crypto stack they have to learn.
“We have to cater to folks who are here for stablecoins only, and we have to cater for millions of users of Stripe who are just using fiat rails,” he said. “A huge part of crypto's value is the fact that it's built on an open and modular stack, and we want to make sure that our users get to mix and match their stack in exactly the way they want.”
Stripe is also exploring tokenized deposits, decentralized finance (DeFi) use cases and accepting more digital assets as payments, Stern said, but “by and far, the bulk of our work happens with stablecoins.”
As stablecoins move into regulated finance, APAC is becoming a key proving ground. This report maps the region’s rules, use cases, and RLUSD’s role.
Asanat Analysis — Why it matters
Stripe's expansion to 100+ countries signals institutional confidence that stablecoin rails can compete with traditional payment infrastructure at scale. The move follows years of regulatory clarity in major markets and suggests the company sees sufficient compliance frameworks to justify global rollout. This represents tangible adoption momentum beyond speculation—Stripe processes ~$1T annually, so even modest stablecoin penetration would dwarf current on-chain payment volumes.
The parallel exploration of tokenized deposits and DeFi integration indicates Stripe is positioning stablecoins as infrastructure connectors between traditional finance and decentralized applications, not standalone payment tools. This bridges a critical adoption gap: merchants and consumers need reasons to prefer stablecoins beyond ideological arguments. Tokenized deposits (likely USDC or similar) enable direct yield or composability, creating utility beyond remittance savings.
Historically, payment processors enabled cryptocurrency's previous adoption cycles but often retreated during downturns. Stripe's explicit crypto commitment and senior hire (Henri Stern) suggests structural conviction rather than cyclical positioning. However, success depends on regulatory stability—any major jurisdiction reversing stablecoin approval could disrupt the global expansion timeline and investor confidence in payment-layer tokenization more broadly.